No. Composition taxpayers cannot claim input tax credit under GST.
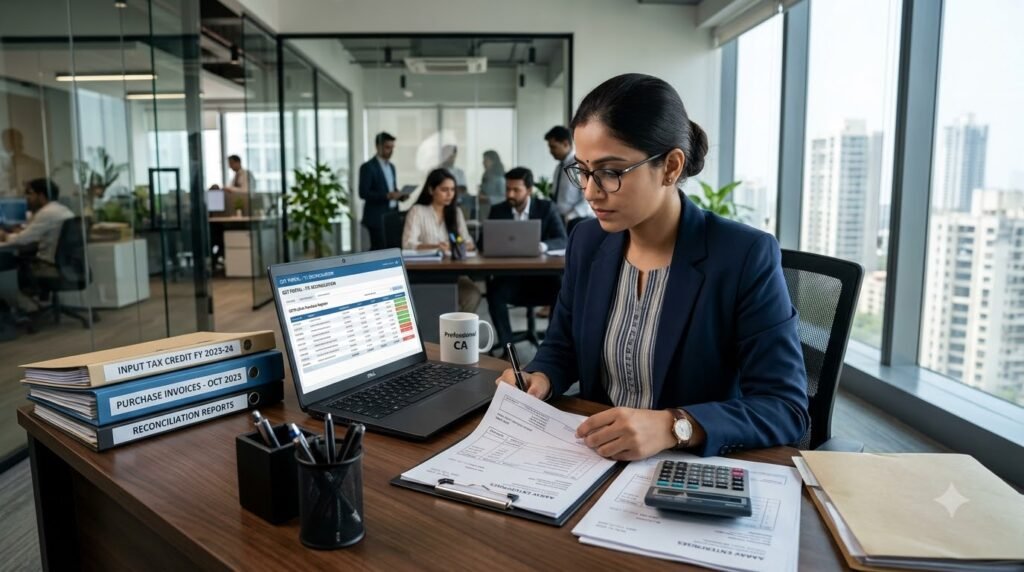
Input tax credit under GST is the mechanism that stops tax from piling up on tax as goods and services move through the supply chain. In simple words, it lets a registered business reduce the GST it owes on sales by the GST it has already paid on purchases. Used correctly, ITC lowers your cash outflow and protects your margins. Used carelessly, it invites notices, interest and reversals.
This guide explains input tax credit under GST in plain language: who can claim it, the conditions, the time limit, blocked credits, reversal cases and the correct way to claim it.
Input tax credit (ITC) is the GST you pay on goods and services used for your business, which you can then set off against the GST you collect from customers.
A simple example: A manufacturer buys raw material worth ₹1,00,000 and pays ₹18,000 GST at 18%. He sells the finished goods for ₹1,50,000 and charges ₹27,000 GST. Without ITC he would deposit ₹27,000. With input tax credit under GST, he deposits only ₹9,000 (₹27,000 minus ₹18,000). The rate is used only for illustration.
ITC is available to a registered person under the regular GST scheme for goods, services or capital goods used in the course or furtherance of business.
It is not available to:
Under Section 16 of the CGST Act, you can claim ITC only if:
There is one more rule to remember: if you do not pay your supplier within 180 days of the invoice date, you must reverse the ITC (with interest). You can claim it again once you make the payment.
For capital goods, you cannot claim depreciation on the tax portion if you have claimed ITC on it.
The time limit for input tax credit under GST is strict. ITC on an invoice or debit note must be claimed by 30 November following the end of the financial year to which it relates, or the date of filing the annual return, whichever is earlier. For example, for invoices issued in FY 2025-26, the deadline is 30 November 2026 (or the annual return filing date, if that comes first). Missing this window means losing the credit permanently, so do not leave claims to the last minute.
Not every purchase qualifies for input tax credit under GST. Section 17(5) lists supplies on which ITC is blocked, even if they are used for business. The main ones include (with certain exceptions):
The exceptions are specific, so check them in the CGST Act, available on the CBIC website, before claiming or rejecting a credit.
Input tax credit under GST must be reversed in these situations:
Reversals are reported in GSTR-3B, and interest may apply for credit claimed and used wrongly.
Once you have claimed input tax credit under GST, it must be used in a fixed order:
Any remaining liability is paid in cash.
These mistakes most often cause trouble with input tax credit under GST:
ITC errors are expensive, and most of them are avoidable with regular reconciliation. Our team at Complete Tax, Ganj Basoda, helps businesses manage input tax credit under GST with confidence:
Contact no.- +91-7898701724 / +91-7898701725
Email- completetax2020@gmail.com
Address – Near Indane Gas Agency, Mill Road, Ganj Basoda, Near Bhopal (M.P.) – 464221 🔗 Contact Complete Tax
Every rupee of ITC you claim correctly is a rupee saved. If you are unsure about your claims, our team can review them and set up a clean process for the future.
No. A valid tax invoice, debit note or other prescribed document is a basic condition.
Yes, but it can be claimed only after the last lot is received.
Generally no. Refunds are available only in specific cases, such as exports or inverted duty structure.
No. Composition taxpayers cannot claim input tax credit under GST.
The invoice will not reflect in your GSTR-2B and you cannot claim the credit until the supplier reports it.
WhatsApp us